Balancing act
Britain's green transition must not swap one dependency for another, writes Narmin Nahidi
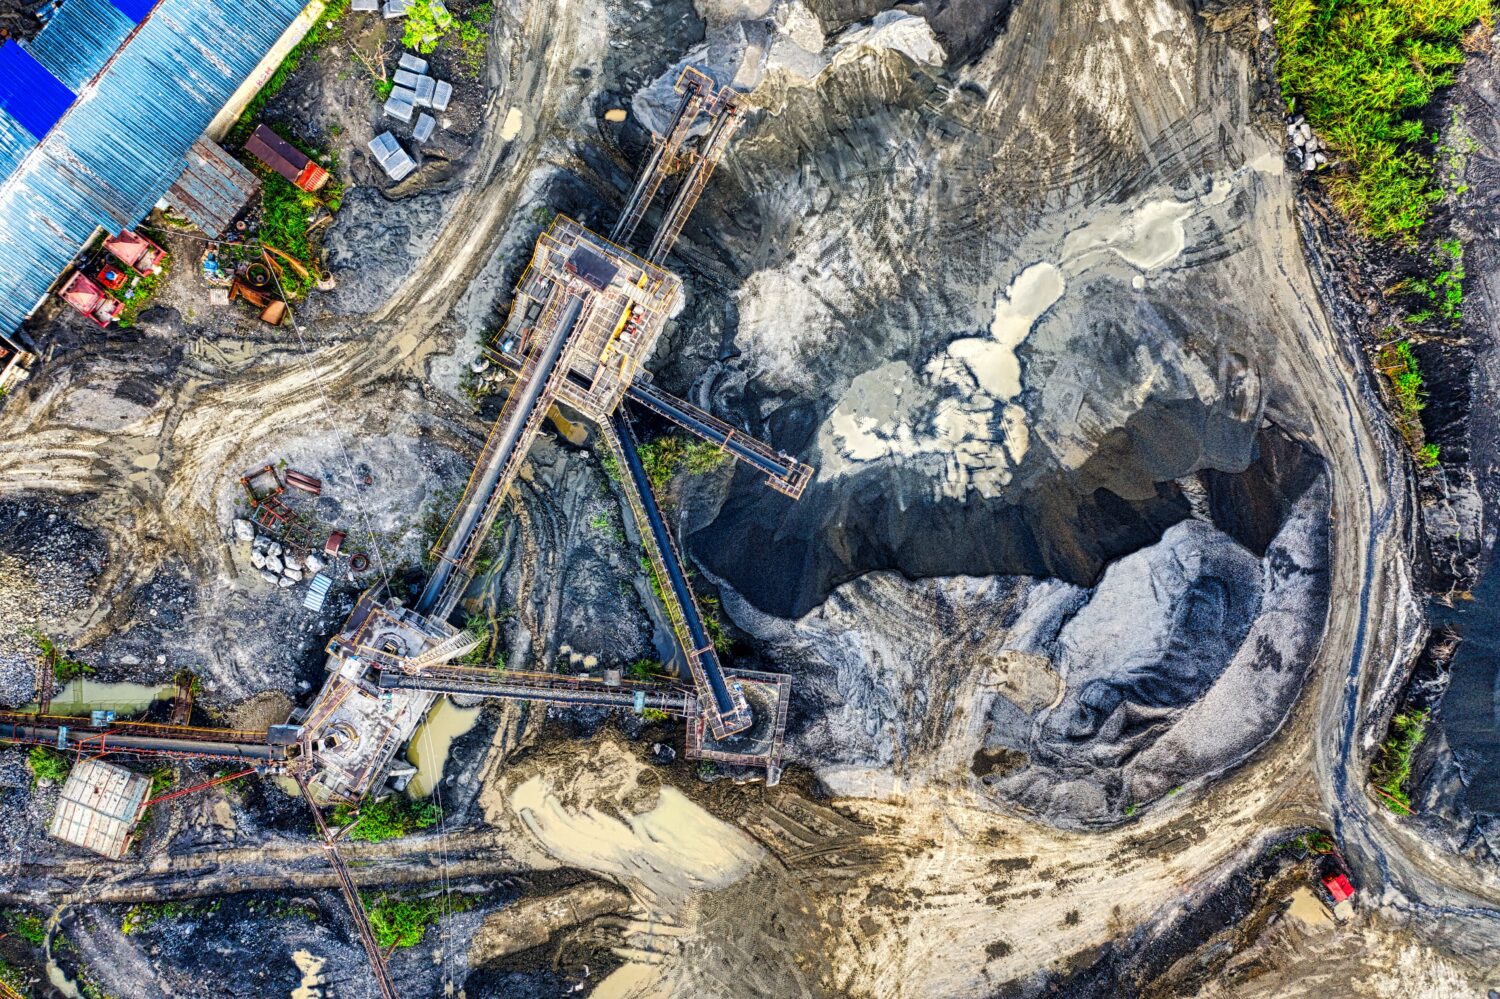
Britain’s transition to clean energy is often presented as a route to energy independence. But wind turbines, solar panels, electric vehicles, batteries and upgraded electricity networks require large quantities of copper, lithium, nickel, cobalt, graphite and rare earth elements. While the case for moving away from fossil fuels remains overwhelming, this presents an important question: will Britain’s transition to cleaner energy simply replace one form of dependence with another?
The immediate problem is the concentration of mineral supply chains. China controls around 70 per cent of rare-earth mining and 90 per cent of rare-earth refining. It also holds a strategic position in the production of solar panels, batteries and the processing of several other (ie not rare-earth) critical minerals – the product of sustained industrial policy, large-scale investment, infrastructure and manufacturing capacity.
Britain cannot reproduce that entire system at home, and complete economic separation from China would be neither realistic nor desirable. Overdependence, however, creates risks. China’s export controls have shown how quickly a commercial supply chain can become a source of geopolitical leverage. At the same time, growing competition for lithium, copper, nickel and other minerals could give producer countries greater bargaining power. As a result, countries in Africa, Latin America and Asia could increasingly shape investment terms, trading relationships and diplomatic alliances.
The social consequences matter just as much. Mining can create employment and public revenue, but poorly governed extraction can displace communities, pollute water and expose workers to unsafe conditions. A green economy in Britain cannot be built by transferring environmental damage and labour exploitation overseas. That would be morally indefensible and politically fragile.
The government’s critical minerals strategy aims to meet 10 per cent of UK demand through domestic production and 20 per cent through recycling by 2035. These are useful ambitions, but targets alone will not create investable projects. Mines, processing facilities and recycling plants require large initial investments, face uncertain commodity prices and must compete with established overseas suppliers.
This is where finance becomes central. The government should use the National Wealth Fund, UK Export Finance and public procurement to reduce strategic risks that private investors cannot reasonably carry alone. Co-investment, loan guarantees and long-term purchasing agreements can provide credible projects with more predictable revenues. In a small number of genuinely critical markets, carefully designed price support may also be justified.
Of course, public money must secure public value. Any company receiving support should meet clear standards on emissions, environmental restoration, worker protection, tax transparency and consultation with affected communities. Public investment should also secure fair returns for taxpayers: the state should not absorb the risk while private shareholders retain all the rewards.
A successful industrial strategy must also address Britain’s regional inequalities. Domestic lithium projects, rare-earth magnet production, mineral processing and battery recycling could create skilled, well-paid jobs in places that have borne the cost of industrial decline. Britain has genuine strengths in finance, engineering, geological expertise, offshore services and research. Policy should connect these strengths to training, local supply chains and secure employment rather than subsidising isolated factories whose profits and decisions sit elsewhere.
Recycling deserves particular priority. Recovering lithium, cobalt and rare earths from batteries, electronics and industrial equipment can reduce waste and limit exposure to global markets by building a circular economy in which materials remain productive for longer.
Overseas diversification is equally necessary. Britain should develop durable partnerships with countries such as Australia, Canada, Chile, Indonesia and Zambia. These agreements must not simply reproduce an extractive model in which minerals leave while most value is created elsewhere. Producer countries should be supported to develop local processing, skills and infrastructure with access to finance and technology. More equal partnerships are both ethically preferable and more likely to endure.
Relations with China therefore require balance. Britain should remain open to trade and cooperation where interests align, while diversifying suppliers, scrutinising ownership of strategically important assets and coordinating with allies. The aim should be resilience, not an economically damaging new cold war.
Clean energy can make Britain more secure, prosperous and fair. But this outcome is not automatic. The government should judge the transition not only by the number of turbines, panels and batteries installed, but by whether it lowers bills, creates good jobs, reduces regional inequality and shares risks and rewards fairly. Minerals, finance and social justice must be treated as parts of the same national project.